Showing posts with label Shopping. Show all posts

Sunday, April 10, 2011

Lessons Learned

If your outgo exceeds your income, your upkeep will be your downfall.

Truer words were never spoken. My grandfather has said that to me many times, but for whatever reason it didn't stick properly. It would have been great if it had! The last year and a half have been a huge learning opportunity for me. It took me a solid month to write the last two posts, because it was a hard pill to swallow. I dug myself into $19,000 of consumer debt in 1 year. 1 STINKING YEAR!

I get nauseated just thinking about it, but I have to do it. If I didn't think about it, I wouldn't learn anything from it, and I'd be setting myself up to fall again. God only knows where the floor would be next time.

Thankfully, I have managed to learn a few things from this experience. Hopefully in sharing them with you all I can prevent someone else from having to learn it the hard way.

You Need A Budget

This is a surprise to no one. At least, it should be a surprise to no one. This doesn't mean that you need to be categorized and itemized down to the cent in a fancy budgeting program, this just means that you need to know how much is coming in, and where it is going. If your income just barely covers your costs, should you really be going on that ski trip or buying a new wardrobe? Probably not. But unless you know where your money is and where its going are you going to be able to turn it down? Again, probably not.


Be Aware Of Your Income

Different incomes can afford different lifestyles, this isn't a surprise for anyone. Readjusting to a lifestyle on a lower income when you've been riding high for a while... that can be a bit of a shock, and not a pleasant one. It requires being cognizant of how much money you have (budget anyone?), and what it will afford. Anyone changing to a job with lower pay, losing hours, or losing a job altogether will have to deal with this at some point, its best to walk into it with your eyes open.

Life Changes Require Buffers

That lifestyle adjustment I mentioned above takes time, and time is money. Getting adjusted before the change, or having some money put aside to help with the change, will be a HUGE asset. Likewise, if there is another major change coming, such as buying a house or welcoming a baby into the world, you'll want a buffer. Chances are it's going to cost you more than you expect.

Get It In Writing

I thought I had learned this lesson while I was working up north, but apparently I didn't. If it's not written into a contract, it's not guaranteed. Overtime, bonuses, and other perks sound fine and dandy when you're negotiating your wage, but unless you get it in writing you can't rely on it. You need to make sure that you can cover your bases using what's on the page, and what's on the page only. Anything else is gravy.

Distinguish Between Needs and Wants

This one really is a gimme.

I NEED enough food that my body can function properly.
I WANT that Starbucks Chai Latte in the morning because they're yummy...

I NEED enough clothing to keep me appropriately dressed for work and the elements.
I WANT that Lululemon top even though I already have a closet full of clothes

I NEED some way of communicating with people
I WANT an iPhone and MacBook Air.

See where I'm going with this?

If You Can't Afford It Now, Chances Are You Can't Afford It Later

What is actually different between now and later? Are you getting a raise? Is there an inheritance coming? Are you going to cut something out of your daily spending habits? Are your expenses suddenly going to drop?

Is anything different? At all?

If nothing is different, and you can't afford something now, how is it you expect to be able to afford it later when the credit card bill comes in? The easiest answer to this is you can't. Especially when the next payday comes around and there is something else you want...

Find Healthy Outlets For Stress

I use shopping as an outlet for stress. It's a horrible fall back, and I'm actually not sure when it started. I can pinpoint when I started using debt for consumer spending, but I can't pinpoint when I started using shopping as an outlet for stress.

I know there are many, healthier, ways of dealing with it. Exercise it one of the better ones, and I find going to a yoga class or going for a run definitely help me cope with things better. So does getting a hug from a loved one. Seriously, hugs are my emotional/mental saviour. I'd probably be a total nut case if it wasn't for the occasional personal contact.
If I don't deal with the stress issue, my spending goes through the roof. Funny enough though, I don't always have to buy consumer items to get that relief. A little while back I was feeling stressed about my finances, so I put a little more money on one of my debts. It's like I'm slowly buying back my freedom, and it worked to sooth my nerves. Any action that reduces the stress levels without getting you further into trouble is good in my books.

Speak Up

Chances are if you have/had a high paying job, you also have friends with high paying jobs. They may want to do things they automatically assume you can afford, because they can afford to. They're not going to know otherwise until you actually speak up that you can't afford it, so do it! You just might find that some of them are in the same boat as you, and are grateful you spoke up.

Control Your Impulses

And for that matter your daily habits. Do you cave and buy something every time you walk past a bakery or coffee shop? This week try just walking past it once. Maybe on a Tuesday. Just see if you can do it once (I know you can). Once you've done it, try it again next week. Maybe on a Thursday. The point of this is to show yourself that you don't NEED to cave every time you walk by. You are strong enough to say no. Willpower is like a muscle; the more you use it the stronger it gets. You might find after doing it for a while you won't have to make a conscious effort anymore and it will just come naturally.

Plan For The Future

Long story short: it's coming, so get ready.

Whether it's an old jar you put your recycling money into, or an investment account you throw half of your paycheck into, everyone needs to save something. Retirement, investments and emergencies all require money, and it doesn't appear out of nowhere. Despite how it may feel every little bit helps, so snowflake away. You'll be glad you did one day.


Anyway, that's what I've learned over the last year and a half. I'm sure there are more lessons in my future, but for now I'm doing my best to apply these ones.

Friday, April 8, 2011

Tipping Point (A Confession) - Part 2

Continued

For those of you who are new to this blog, I'd suggest checking out yesterday's post before reading this one. It will make more sense all together. But for the rest of you, continuing on:

April 2010

Having put well over $10,000 into my RRSPs the year before, along with the new homebuyer's tax credit, renovation tax credit and professional dues tax credit, I figured I'd be in for a pretty solid tax return. Imagine the nasty surprise I got when I found out that not only was I not getting a tax return, but I OWED the government money. My former employer did not take off even CLOSE to the amount of tax they should have been taking off. 

Oh to have been a fly on the wall in my room that day...

All of those RRSP credits and other tax deductions went towards my balance owing, and I ended up paying the government several hundred dollars. On top of this, I was now carrying a debt I had been expecting would disappear when tax time came around.

The only upside to this month is that I got a small raise at the end of my probationary period, and my salary was now sitting at $54,100.

May 2010

Despite the financial slap I got in April, I stayed the course of spending without paying attention to my accounts in May. Nothing really noteworthy happened this month.

June 2010

The tax assessment for my house came in, and it was higher than the previous year. My biweekly accelerated mortgage payments went up another $50, which really sucked. However, I wish that's all that had happened this month.

I had an emotional upheaval in the relationship department on the order of: boyfriend's other girlfriend sends me a message on Facebook basically saying "Hey, I've been dating _____ for a few months. He's met my friends and family, I'd like us to be friends too :)"

Yeah, you read that right.

She had no idea he'd been seeing me for years, and that I was waiting for his work to run it's course so that he could come home again. He had made it sound like I was a really close friend to her, and he had made her sound like "the guys from work" to me. He was working out of province at the time.

I soothed that pain and rage with personal spending like nobody's business.

July 2010

July was a lot of carry over from June. I had emotionally shut down and start culling my emotionally draining/toxic friendships. My now pseudo-boyfriend was trying his best to perform damage control on the relationship, and I just couldn't care less. Needless to say I didn't really pay attention to my finances this month other than my month end update. I can tell you that update wasn't pretty, but I still maintained the position of the proverbial ostrich with my head in the sand.

August 2010

My boyfriend came home for a couple weeks and tried frantically to patch things up with me. I was still pretty checked out and emotionally spent, but I let him try. I wanted to believe things could get better again. I was naive, and it did a huge number on me.

Outside of the relationship realm, I wanted to finish the renovating my kitchen before the snow hit, so I bought more construction supplies for my home. I also pre-paid a hotel room in Vancouver for a couple days in the next month. I needed to be within a reasonable distance of Stanley Park for the Vancouver Triathlon, and there really wasn't much in that area that was either a) cheap, or b) not booked full.

September 2010

I knew at this point that I had to do something about my money, I was beginning to feel the pinch when it came to paying the bills every payday.

I was also freaking out in the personal department, because there was a distinct possibility that I was carrying a little mini me. This was causing me a LOT of stress.

After finishing the triathlon in Stanley Park I went back to my hotel for a bath, some soup and some tea. After warming up a bit, and taking my bike apart again for the plane ride, I made the misguided decision to walk around the shops in Vancouver for a while.

Now, I'm in love with trench coats. I have wanted a Burberry trench coat, no word of a lie, since I was 12 years old. God only knows what a 12 year old knows about clothes or what they cost, but I've been stuck on this coat since then. Through all of the seasons and different styles, it has never changed: beige, knee length, dark buttons. I had been looking for one in my size since university, with no success. I searched for it like Bridget did in her the hunt for the Herve Leger dress over at hithatsmybike.

I found one.

In a moment of sheer stupidity fueled by high running emotions, I emptied out what savings I had to pay for it. It wasn't enough. Despite swearing up and down to myself that I would never do this, I called my credit card company and had them increase the limit. For a coat.

That afternoon I bought a Burberry Manston Trench. $1595+HST. I've kept the price tag as a painful reminder of that; it's sitting on my dressing table at home.

What should have been an exciting purchase (I've wanted it for over a decade...), made me sick to my stomach. What the hell did I just do? I couldn't return it, the store was closed and my flight left before it opened again in the morning. I sat on my hotel room bed staring at the bag wanting to be sick. I was having a hard enough time paying the bills, how was I going to pay for this too? What if I am pregnant, how am I going to find the money to raise a kid? What if I have to do it by myself? What am I doing??

I had a problem, and I needed to do something about it. My money was out of control. Seriously, a year ago the only debt I had was my car, what on earth had gotten into me?

I promised myself I was going to turn this around.

October 2010

I started this blog.

Now I'm digging my way out and up.

Monday, April 4, 2011

Looking Forward - A Shopping Preflection

I was thinking about the upcoming month in terms of spending on my bus ride into work this morning. I know a lot of people set monthly spending goals ($1000 a month for everything above rent or something similar), but it's not something I really want to get into yet. I feel like my months are still quite variable in terms of spending, and I don't want to put off doing something because of an arbitrary figure I've chosen for myself. It's awesome if it works for everyone that's doing it, I just don't think I'm ready to hop on the bandwagon yet.

Especially not this month :s

Anyway, I was thinking about the spending because I realized that this was going to be a kind of expensive month for me. I need to get 3 things: A weedwacker, a bra, and moisturizer. It doesn't really sound expensive at first, but if I can't find cheaper alternatives it's going to set me back about $500 (minimum) for those 3 items.

The moisturizer is kind of a non-negotiable item for me. Some of you might remember back in December when I was struggling with the price of the stuff. Well, fast forward a few months and I can honestly say I'm not going back. My skin doesn't hurt when I wash my face anymore, and I don't have to avoid touching it for fear of rupturing something. The cyst I spent over a year trying to get rid of finally disappeared, and the scarring is slowly healing. The jar is almost empty, and I'm going to have to switch to the lotion as the cream is getting to be a bit too heavy as it gets warmer out. It's cheaper per ounce, but comes in a larger container. This is going to set me back at least $240. I'm going to try to time it to line up with a gift with purchase or something, because the stuff doesn't go on sale.

The bra is a bit of a contentious issue for me. You could say that I developed early as a kid. I started wearing a bra in grade 6 or 7, and by the grade 8 I was easily a C cup. That would have been fine and dandy if they had stopped growing then (and why not? That's when I stopped getting taller), but they didn't.

Above is a bra sizing chart. The areas outlined in green are approximately your standard bra sizes. That little red splotch over to the left? That's me. I don't even make it on to the chart. I spent much of my teenage and early adult bra shopping years crying in change rooms because nothing fit, and anything that came close looked like something your grandmother would wear. My mom has the same problem. A few years ago after I moved to Edmonton to go to University I found a bra shop that carried my size.

HALLELUJAH!

The shop specializes in bras and specialty sizes. They order their stock in from Europe, where you can actually get a wider range of sizes. Not only that, for the first time in my life I could get a pretty bra. I think I cried tears of joy in her fitting room. Unfortunately, they do come at a price, and the last time I bought bras there they were about $160 a piece. The exchange rate has gotten better, so they may have come down in price a little, but I'm not holding my breath on that one. Two of my current bras have underwires that are about to give out (trust me, they hurt when they're stabbing me), so I know this expense will be hitting me soon.

Last but not least is a weedwacker. This is the one where I should be able to get the most pricing wiggle room from. I've only checked 1 store so far, but they're sitting at around $150-$200 for a gas powered one. I'd like to find an electric one, but I'm not 100% set on that. I tried to get by without one last year after I bought my place, and I can tell you it's not going to happen this year. I bought my house during the winter, and come spring I realized I had bought "That house". You know, the one overflowing with weeds in the neighbourhood of pristine lawns. I spent a lot of time last year fighting the weeds, and I'll be doing it again this year. I need to keep the upper hand on them as they can get away from you REALLY quickly, and the city will fine you if you don't keep them under control. My lawnmower doesn't reach everything, so this year I need to get one. I'm going to check out Kijiji and Ebay as well for a used one. The snow is melting here quickly, so I need to get on it soon.

I'm glad payday is Thursday.

Tuesday, March 1, 2011

*slide*

And now, for last month's slips. Needless to say, it was a little rough for me this month, especially around the middle. I'm not going to beat around this one, I slipped into an old, very bad, habit this month. I used shopping to beat stress.

I seriously deserve a beat down for this one.

After what was the hardest day I've had at work in well over a year, I went shopping. I didn't use cash. I did set myself a limit, I wasn't allowed to spend any more than 50% of my extra payments this month. That way by the end of the month I was still digging myself out, it was just slower than anticipated. Still, it's a habit I need to break.

After reading on Hi That's My Bike that the jeans I had been after were on sale at Anthropologie, I trotted down there and picked a pair up. Originally almost $220, they were marked down to $80.  While I was there I noticed the sweater I had been fawning over the weeks leading up to Christmas was marked down to $40 from $120, so I picked up the last one in my size as well. Tack on a couple small gifts for people, and a tube of mascara to replace mine (it was time), and I was done. Part of what limited the shopping (other than the fact that the mall was closing), wasn't so much the fact that it would mean my debt would take longer to pay off, but the fact that I'd have to write about it on here. Let's face it, admitting to this stuff is embarassing. So, thank you all.
Credit Card Damage: $184.64

I love music. I know what I should do here is delete my credit card information off iTunes, go out and buy an iTunes gift card with cash, and then use that. As of yet I haven't done it. Chalk this up to laziness, I'll buy one next time I'm out getting groceries.
Credit Card Damage: $3.57

As many of you probably saw earlier in the month, I signed up for the Ride to Conquer Cancer. Unfortunately there was a sizable registration cost associated with signing up for it.

That's right, I paid money to raise money for someone else.

I don't feel too bad about the cost of the registration because they feed us and provide us with a place to sleep that weekend. I'm basically paying for a weekend out now rather than in June. They only took either credit card or cheque for the registration costs, and I didn't have any cheques on me, so it ended up going on my credit card. That's the problem with having your card number memorized, its still usable even when it's frozen in a block of ice. My only saving grace on that is that while I have the loooooong number on the front memorized, the short one on the back I don't. That means I usually can't use it online. I put extra money on my card the following payday, but it would have been nice if that money went towards paying the balance down rather than just maintaining it.
Credit Card Damage: $75

That's $263.21 in non-cash spending during the month of February.

*facepalm*

That sucks.

Amazingly enough though I didn't use my debit card all month, other than to take money out of the bank machine every payday. I did however write down and track my spending all month, which was one of my other goals for February. I'll post the results of that tomorrow :)

Tuesday, February 1, 2011

*slip*

As some of you remember from my New Years resolution post, one of my goals for this year was to go cash only in my purchases. For the most part I've been quite successful. There were some slips in January however, and I feel that for the sake of keeping myself accountable, I should put them up here.

Our company had it's Christmas/New Years party the second weekend in January. I think they had started planning the party a little late and all of the good venues had filled up, so they moved it into the new year. We had an evening in the ballroom of the Fairmont Hotel MacDonald. Absolutely gorgeous.
I love this hotel

I had a dress picked out that I planned to wear for the evening. We're not a super stuffy office at work, there's only a handful of guys that wear suits, and that's only if they have a client meeting that day. I figured it would be suitable. The day before the party I was talking to one of the ladies in the office, discussing what we were going to wear. I described the dress and her eyes got wide and she said "Oh no, that's not fancy enough. It's a semi-FORMAL cocktail party".

Well crap.

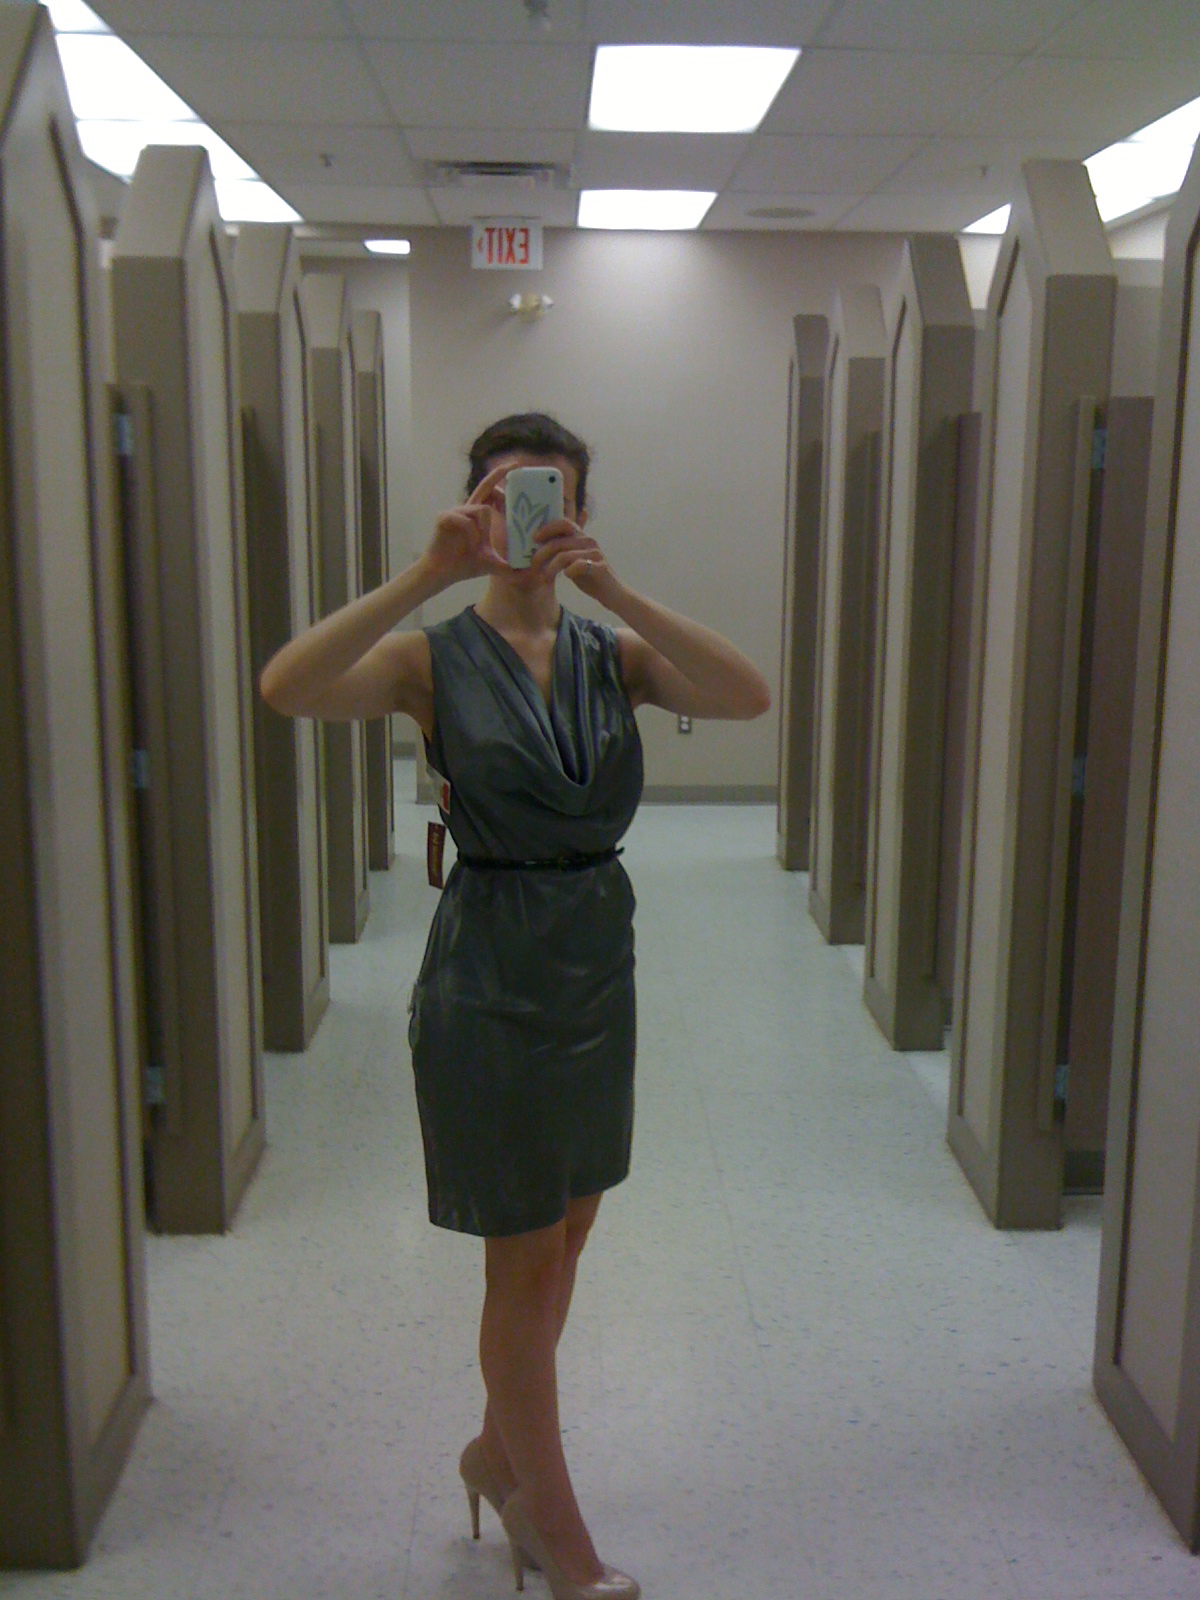
I went home and raided my closet only to discover that the dress I was planning to wear was the most formal thing I owned before it jumped to my all out formal graduation dress. So Saturday afternoon, the afternoon before the party, I was doing the mad dash power shopping in West Edmonton Mall. How bad could it be, all the New Year's dresses should be on sale, right? Wrong. Almost every store I hit had already cleared out their party gear, leaving me pretty hooped for well priced selection. I ended up scouring the racks in Winners, coming up with just 2 dresses in my size. I ended up settling on this silver silk Michael Kors cocktail dress. It was originally $225, marked down to $77. A bit more than I wanted to spend, but I was short on time. The picture doesn't do it justice, but lets face it, what more do you expect from dressing room lighting? Debit Card Damage: $80.85

The next one really was no more than lack of restraint. I should have gone home, grabbed the money, and come back. Instead, I shopped impulsively. I really need to work on that. Victoria's Secret was having a clearance sale: 10 pairs of underwear for $20. I don't remember when the last time I got underwear for $2 a pair was. Thankfully (and kinda sadly) their bras don't actually fit me, so the damage was somewhat curbed in that respect. I'd been meaning to get some underwear, so that was a plus. Right price, wrong method of payment. I accept responsibility for this one. Debit Card Damage: $21.00


This one was related to me being sick for a couple weeks. After a week of being sick, and nothing really helping to curb it, it occurred to me that what I was feeling felt more like a sinus infection than a cold. I checked online, and sure enough the symptoms were a direct match. Monday I went in to the doctor's office to be checked out. Sure enough, sinus infection. So, out came the prescription pad. Rather than going home and getting the cash out of my envelopes and picking up the drugs the next day, I bought them immediately after the doctor's appointment. I already had a raging sinus headache, and I was looking for relief. Debit Card Damage: $14.64
The last one was a case of me breaking down and buying some music on iTunes.
Credit Card Damage: $8.43

Total non-cash damage: $124.92. The rest of my spending for the month of January was done with cash: eating in, eating out, socializing, toiletries, you name it. Not good, but much better than it would have been otherwise if I wasn't trying to go cash-only. It's definitely making me rethink and plan my spending.  I'm hoping February goes a little better, because I really don't know what happened with my finances last month.

*Forgot a date. Spent $3.50 on hot chocolate. Total damage $128.42*

Thursday, November 18, 2010

Jingle Bills, Jingle Bills, Jingle all the way...

So, I stayed under budget last pay period enough that I broke even budget wise over the last month. Yay!

But danger is looming.

It’s really close.

It’s…. the holiday season… *cue scary music*

That’s right, it’s the holidays again. As I mentioned before, my mom’s birthday, my dad’s birthday, and Christmas all fall within just over a month of each other. Do you smell something burning? That’s my wallet.

I had planned on making everyone gifts for Christmas (knitting scarves, sewing shoulder bags, making cookies and candy), which I realized recently wasn’t going to happen due to the amount of time it would take and how much time I actually had to work with. That and I remembered how much Canada Post was going to charge me to mail that stuff to my grandparents.

Then I remembered how much it was going to cost to express post them if I was late getting them out the door again.

So, my mom and I were discussing Christmas gifts today, and I broached the subject of putting a budget on the upcoming holidays. Thankfully, she was receptive to the idea. We agreed on a budget of $150-$200 per person for Christmas. Before you raise a stink that it’s an exorbitant amount of money, I’d like to point out that our usual budget is I-want-to-give-you-the-world-and-so-I’m-going-to-try-until-my-bank-account-is-empty-and-my-cards-are-racked-up. $150-$200 is a sizable step down.

Which is bringing me to my current transgression…

I’m going Birthday/Christmas shopping today, and using my line of credit to do it. I feel like slapping my own hand for typing that, but it is what it is. That way I can ship the gifts out using regular postage, and I can pay it off leading up to Christmas. I’ll spend about $5 in interest charges over the course of the month, and save WAY more than that in postage.

*SPOILER ALERT*

As for that cute packaging I bought for the baked goods I was going to be making? My friends are still getting homemade candy. Not a complete loss there.

*END OF SPOILER ALERT*

Those shoes I broke a while back and was going to get fixed? I talked to the cobbler yesterday, they're a lost cause. That's one big pouty face going on over here right now.

Monday, November 15, 2010

Still Under Budget!

I'm back from my long weekend, and I didn't blow my budget! I went down to Calgary, ate junk food on the road, went for a nice sushi dinner, hung out with my cousins, picked up some styling cream for my hair and went skiing... all for under $200. Score. I didn't budget smooth this pay period persay, but I didn't blow it either.

I've been thinking a lot about why I don't feel like I have anything to wear to work. It's not that I don't have clothes (I have a ton of them), I just realized that I don't have the right ones. For example, I'm currently missing:
  1. A Suit
  2. Black Pants
  3. White Collared Shirt
  4. Plain Black Pumps (mine are now all either stretched out or broken)
  5. Jeans I can tuck into boots (so they don't get soaking wet when the snow flies)
  6. Sweaters in between the paper thin and bundle up at home thicknesses
  7. A Purse for work that's in acceptable shape
Not included in the list is the annual pair of ballet flats that I've walked my way through. I say annual because I wear them out and they never last longer than a year. It's no wonder I feel like I'm scrambling even though I have a pile of clothes. I used to have all of the items on the list. Sadly I either didn't spend the money on them and they didn't last, or I wore them to death. I'm trying to figure out how to remedy this without back tracking on my progress. I'm thinking that Boxing Day sales are going to be used for part of this.